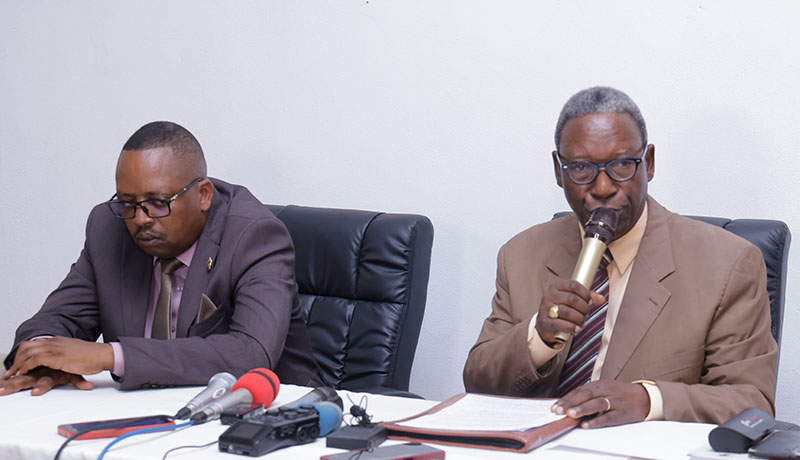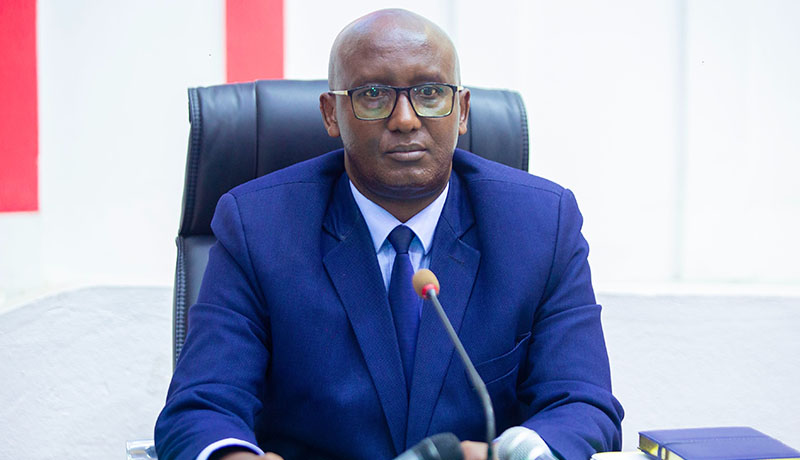
Léopold Kabura, president of the Court of Accounts, presented a report on public finance control to the National Assembly on 15 October 2026. The findings revealed that for the 2025-2026 fiscal year, only 12 out of 303 public entities submitted their accounts to the Court of Accounts.
Léopold Kabura stated, "Le nouveau texte régissant la Cour des comptes devrait introduire des sanctions pour les institutions défaillantes."
Faustin Ndikumana, national director of Parcem, addressed the lack of compliance, asserting, "Donc, il n’y a pas de volonté politique au plus haut sommet pour lutter contre la corruption. Parce que c’est la volonté politique, la Cour des comptes est un instrument par excellence. Dans plusieurs pays, la Cour des comptes est l’indicateur d’une bonne gouvernance financière dans un pays et de renforcement de la gestion démocratique du pays."
Widespread Failure in Reporting
No province or commune in Burundi submitted their accounts for the 2025-2026 fiscal year. Within the central administration, public administrative establishments, and personalized state administrations, only four out of 38 entities provided required financial documentation. Public investment projects also failed to comply, as none of the 35 projects submitted their accounts. Additionally, only five out of 141 hospitals reported their financial activities to the Court of Accounts.
Diomède Ninteretse, économiste et expert en leadership, described the lack of compliance: "C’est une grande irresponsabilité de certaines autorités politiques du Burundi. C’est une honte, voire une situation catastrophique, parce que je dois vous dire que la reddition des comptes représente pour moi une rencontre entre trois exigences de l’État moderne."
Constitutional Mandates and Deadlines
Article 182 of the Burundian Constitution establishes specific requirements for the submission of financial accounts by public entities. According to this mandate, all institutions must deposit their financial records with the Court of Accounts no later than 30 September. This deadline is set exactly three months after the conclusion of the fiscal year, which ends on 30 June. The constitutional framework aims to ensure timely oversight of public resources by requiring organizations to finalize and report their fiscal activities within this established timeframe. Strict adherence to these dates is intended to facilitate the assessment of state financial management, providing the necessary documentation for the Court of Accounts to perform its functions as defined by the national legal standards.